
Macro Fundamentals vs. Market Realities (NEPSE)
The Disconnect Between Nepal’s Economy and NEPSE
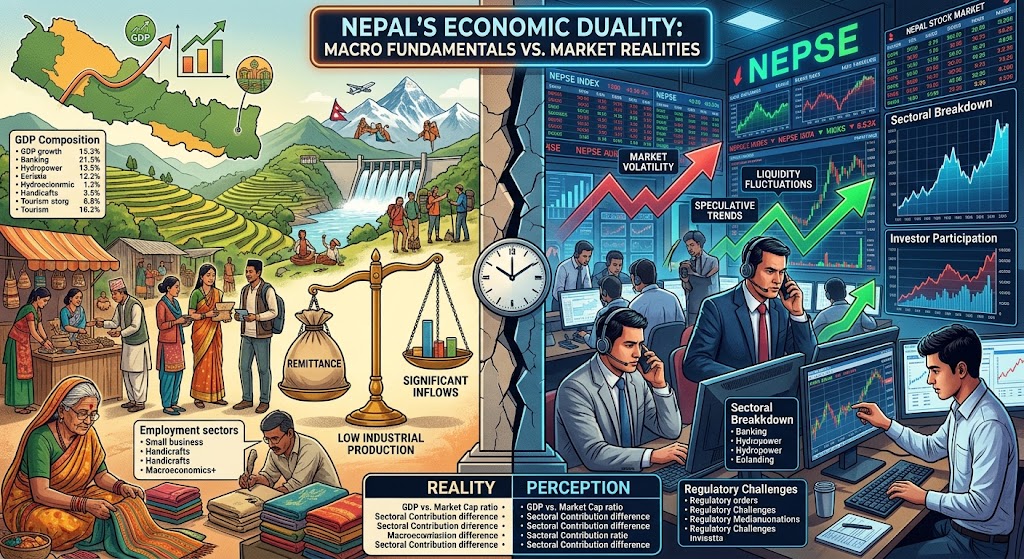
Nepal’s capital market and its broader macroeconomic health continue to show a pronounced disconnect. While macroeconomic metrics demonstrate resilience—backed by strong remittance inflows and modest GDP expansion—the Nepal Stock Exchange (NEPSE) operates largely on market liquidity, commercial bank interest rates and retail sentiment rather than underlying economic productivity.
Macroeconomic Snapshot vs. NEPSE Performance
| Macro Metric | Economic Data Point | NEPSE Correlation & Market Impact |
| GDP Growth | 3.99% multi-year recovery rate | Weak Linkage: Agriculture (25% of GDP) and key manufacturing sub-sectors remain unlisted. |
| Market Cap to GDP | 77.7% – 82% of GDP | Elevated Valuation: High relative ratio driven by limited floating stock rather than underlying corporate output. |
| Remittances | Growth exceeding +37.7% | High Direct Impact: Primary liquidity engine fueling retail stock trading and bank deposits. |
| Weighted Lending Rate | 8.40% | Strong Negative Correlation: High borrowing costs constrain margin lending and squeeze market turnover. |
| Deposit Interest Rate | 4.54% (Risk-free alternative) | Divergence: Deposit yields lower investor appetite for equities. |
| CPI Inflation | 3.62% | Real Return Erosion: NEPSE nominal gains yield marginal real inflation-adjusted returns. |
Key Structural Disconnects
- Narrow Sectoral Representation
Although agriculture accounts for approximately a quarter of Nepal's total domestic output, it is virtually unrepresented on the exchange. NEPSE is predominantly weighted by financial institutions (banks and insurance), hydropower companies and investment firms. Major economic drivers—such as major manufacturing conglomerates, international hospitality and agricultural production—remain overwhelmingly privately held.
Real Economy Output (GDP) NEPSE Sector Breakdown
-------------------------------------------------- -----------------------------------------
| Agriculture (25%) | (Absent) | Financials (Banks, Ins.) | 50%+
| Informal & Services | (Absent) | Hydropower | 25%+
| Manufacturing & Trade | (Unlisted/Few) | Hotels & Investment | 15%+
- Interest Rate & Liquidity Sensitivity
Historical trends confirm that NEPSE movements are primarily dictated by commercial bank liquidity and Central Bank (NRB) policy rates rather than corporate earnings growth.
- Margin Loans & Rates: When borrowing rates drop and bank credit opens up, liquidity flows directly into equities regardless of broader economic stagnation.
- Real Returns: Risk-adjusted real returns on bank deposits currently rival equity market real returns, keeping institutional capital on the sidelines and depressing daily trading volumes.
- Participation & Market Depth
While Demat account numbers have grown, active institutional participation, market makers and short-selling mechanisms remain sparse. As a result, the secondary market exhibits high short-term speculation rather than long-term capital formation.
Unless regulatory reforms encourage large private corporations to list publicly and liquidity parameters shift toward lower interest rates, NEPSE will continue to trade based on monetary policy indicators rather than the broader economic pulse.
Tags


Leave a Comments
Comments
Popular
Recent Post
No comments yet.